
Slowio maintains a standing quantitative model of euro area inflation and its implications for Bund yields and European equity valuation, with a Switzerland, UK and world readout, refreshed with sourced data roughly monthly. Each refresh, this digest records what moved since the prior run; the full report — force ledger, scenarios and sources — lives on the permanent Macro Outlook Europe page. Analytical framework output — educational tool only, not financial advice.
This issue: the October 2026 refresh, covering what moved since the prior model run.
Inflation surprised higher, again on energy.
- Headline HICP: the September flash is 3.8% YoY, up from 3.2% in August (Aug revised from the 3.3% flash). MoM is +0.6%.
- Energy HICP: 18.8% (from 14.3%), contributing about 1.7pp to headline.
- Core and services: core HICP is 2.5% (from 2.4%, MoM +0.2%). Services are 3.2% (from 3.0%).
- Big four: DE 3.3%, FR 3.4%, IT 4.1%, ES 5.0%.
- Missing this run: core 3-month annualized and negotiated wages are not available.
- ECB staff projections (Sept):
- HICP 3.0% / 2.5% / 2.1% for 2026 / 27 / 28, with a peak of 3.6% in Q4 2026.
- Core 2.5% / 2.6% / 2.3%.
- Compensation per employee 3.3% in each year.
- September already exceeds the staff-projected Q4 peak.
ECB.
- The prior state's 2.00% deposit rate is superseded. The ECB hiked 25bp on 11 June and another 25bp on 10 Sep, effective 16 Sep.
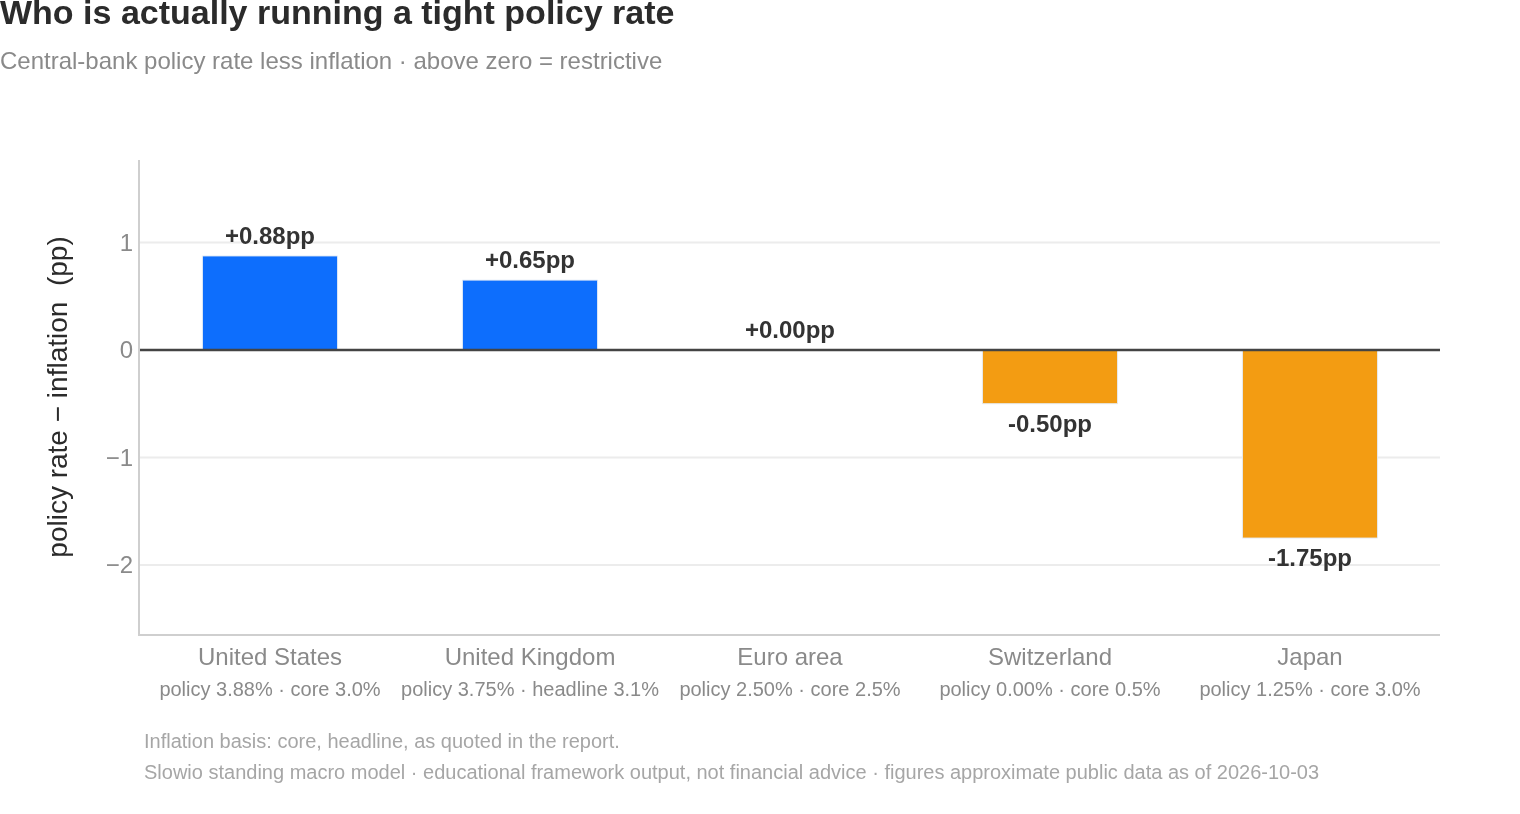
- The deposit facility rate is 2.50% (MRO 2.65%, MLF 2.90%). Meeting-by-meeting guidance is retained.
- Market pricing for the next three meetings:
- October hike odds are negligible or below 30%.
- The next hike is not fully priced until January.
- Up to three more hikes are seen over the coming year.
- €STR was 2.19% and about 40bp of cumulative hikes were priced by end-2026 (as of 9 Sep).
- Meeting-by-meeting OIS figures are unavailable.
- Balance sheet: APP/PEPP run-off continues, and excess liquidity fell about €101bn to €2,117bn.
- Dissent at the September meeting: not sourced.
Rates and spreads.
- 10Y Bund: ~3.47% in the latest quote (3 Oct), versus 3.36% at the prior run (+11bp). It touched a 17-year high, with quotes as high as 3.64% on 2 Oct, before easing below 3.45%.
- 2Y Schatz: 3.00% (2 Oct), versus 2.98% prior.
- OAT-Bund: about 130-152bp across 2-3 Oct quotes (central ~140bp), the widest since 2011-12, versus 80.4bp prior. This follows the French budget presentation.
- BTP-Bund: 116.5bp at the 1 Oct close and 122.5bp in the latest quote. It was unavailable last run.
- Unavailable: EUR/USD, the euro 5y5y swap and the 10y inflation swap.
Equities.
- STOXX Europe 600: 631.35, versus 646.32 prior (−2.3%). The 52-week high is 660.51 (11 Aug).
- Valuation multiples: forward P/E 15.37 and trailing 19.67 are still dated 30 Jun 2026 and flagged STALE.
- Mechanically re-scaled by price (631.35 / 641.73), they would be about 15.12 and 19.35, ignoring EPS revisions.
- Earnings growth: expected Q3 earnings growth is +19.4% y/y, or +9.9% ex-energy. One bank sees eurozone EPS +15% in both 2026 and 2027.
- Euro Stoxx 50: 6,320.26 (30 Sep). Its index forward P/E is unavailable.
Forces.
- TTF gas: EUR 71.9-76.5/MWh (2 Oct), with a 30-day average of 75.89 (range 70.51-82.51). Prior was 73.2-73.7, so roughly flat-to-higher.
- Brent: USD 99.8-102.7, versus ~95 prior.
- Supply news:
- Saudi Arabia restarted the East-West pipeline and Yanbu loadings, but Hormuz transit remains risky.
- European governments are weighing an emergency oil/diesel stock release.
- Fiscal:
- The euro area deficit is projected at 3.6% / 3.7% / 3.6% of GDP for 2026-28.
- The defence escape clause is active for 14 euro area countries.
- An EDP was opened for Bulgaria.
- German package news is unavailable.
- Trade: the US-China "30-for-30" tariff truce covers about $60bn of goods and expires 10 Jan 2027. There is no US-EU tariff item.
- Unavailable: electricity prices, unemployment and China export prices.
Ledger changes (≥0.05pp):
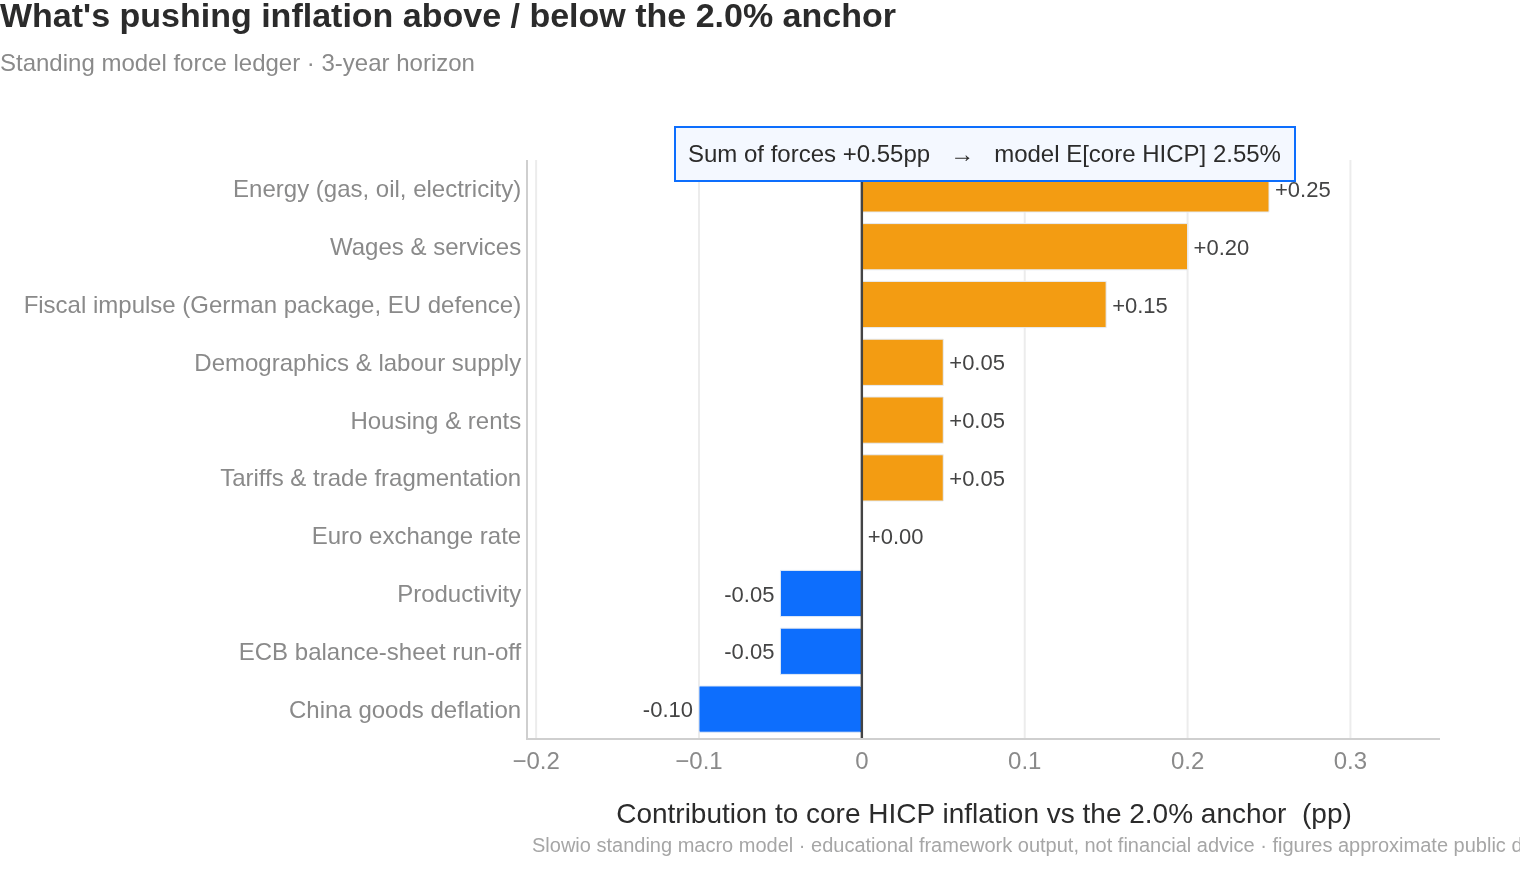
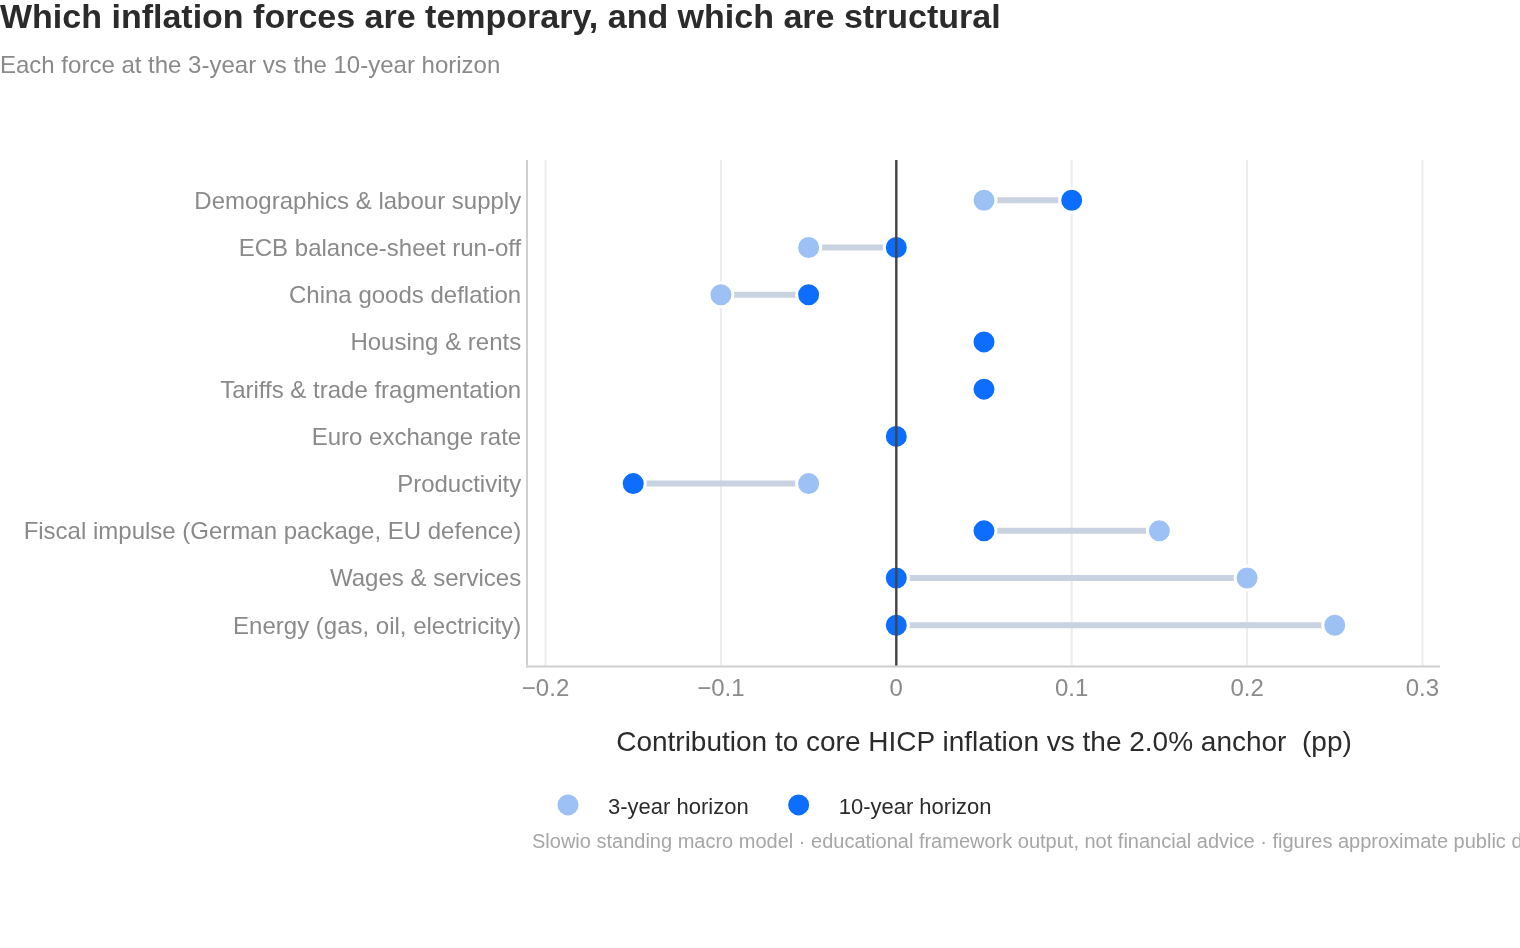
- Energy 3y: +0.20 → +0.25. Brent is near USD 100, energy HICP accelerated to 18.8%, and core and services ticked up, so second-round pass-through into core over 3 years is more likely. All other weights are unchanged.
Scenario changes:
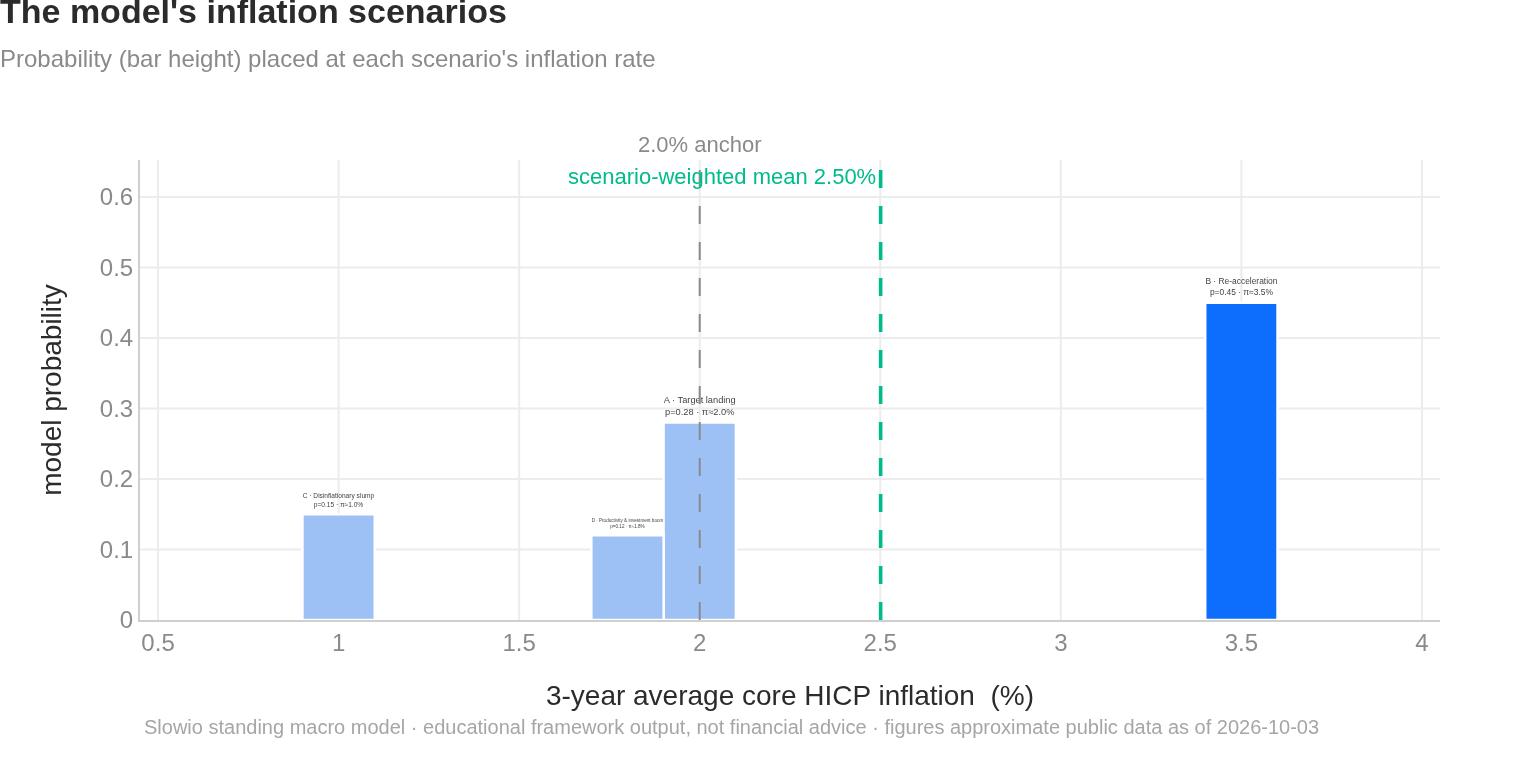
- B: 0.40 → 0.45 (+5pp). Headline at 3.8% already exceeds the ECB's projected 3.6% Q4 peak, services are rising, and staff see core at 2.6% in 2027.
- A: 0.30 → 0.28. Residual.
- D: 0.15 → 0.12. Energy prices are not falling durably.
- C: unchanged at 0.15. Spread widening and a 5%+ UST 10Y tighten financial conditions, offsetting ECB-hike credibility.
Verdict: model moved (modestly).
- Fair 10-year yield: model 3.58% (r* 0.40 + HICP 2.48 + TP 0.70) vs market 3.47% (2026-10-03) (market minus model: -11bp) — Actual 10Y Bund 11bp below model fair value — inside the +/-50bp flag; model-vs-inflation-swap gap not computable (euro 5y5y and 10y ILS absent from clippings).
- Model expected inflation, 3y: 2.55% core (ledger) / 2.50% (scenario-weighted); sigma 0.96pp; P(pi>3%) 39%, P(pi<1.5%) 20%
- Forward P/E vs model fair multiple: Actual forward P/E 15.37 (30 Jun 2026, stale) is 22.5% above the model-average fair 12.55; on the price-rescaled 15.12 the gap is 20.5%
- Model expected returns, 3y: stocks +3.9%/yr · bonds +3.1%/yr
- Model expected returns, 10y: stocks +6.3%/yr · bonds +3.5%/yr
- Highest-probability scenario: Re-acceleration at 45% (inflation path ~3.5%)
Switzerland, UK & world
Switzerland
- CPI: +1.0% YoY in September (0.0% m/m). It was unavailable last run.
- Core CPI: +0.5%, versus 0.4% (Feb, stale) prior.
- SNB: held at 0% on 24 Sep. The discount on sight deposits above the threshold is unchanged at 0.25pp.
- The SNB repeated its willingness to be active in FX markets as necessary.
- It noted the franc has depreciated ~3% trade-weighted since the last assessment.
- EUR/CHF: no new level is available, so 0.9392 (1 Sep) is carried STALE. Market commentary reported EUR/CHF sliding as French spreads widened on 2-3 Oct.
- USD/CHF: 0.8101 (1 Sep), carried STALE.
- Sight deposits: CHF 454.4bn (13 Mar), carried STALE.
- Read:
- Strong-franc pressure eased on a trade-weighted basis over the quarter.
- Renewed euro-area fragmentation (OAT-Bund ~140bp) is a fresh safe-haven channel.
- With policy at the zero floor, negative-rate risk remains the SNB's fallback alongside FX intervention.
- For Swiss-listed exporters: this means a less adverse trade-weighted franc than in June but renewed safe-haven risk versus the euro.
United Kingdom
- CPI: 3.1% in August (prior 2.9% July), expected to rise further.
- Services CPI: 3.4%, unchanged.
- Core CPI: not sourced; 2.6% (Jul) carried STALE.
- Bank Rate: held at 3.75% on 16 Sep, on a 6-3 vote, with three members preferring a hike to 4%. The MPC also voted to reduce its gilt stock to zero.
- Unavailable: the 10Y gilt and GBP/EUR.
- For European-listed companies: a hawkish-leaning BoE and rising UK CPI keep sterling-area financing costs elevated.
United States
- Fed: hiked 25bp to 3.75-4.00% on 16 Sep (prior 3.50-3.75%), with the effective rate at 3.88%. The median dot is 4.1% for end-2026.
- 10Y UST: 5.24% (1 Oct), versus ~4.8% prior.
- Core PCE: 3.0% (Aug), with headline at 3.4%. This replaces the prior ambiguous 3.7%.
- DXY: ~101.5, versus ~99.4-99.8 prior, up ~2% in September.
- Read: this is the main external driver behind the higher Bund term premium, and dollar strength implies a softer euro.
- For European-listed companies: higher global discount rates weigh on multiples, while dollar earners gain translation support.
Japan
- BoJ: hiked at its 17-18 Sep meeting. The level is not stated; it is implied at ~1.25%, since the next hike to 1.5% is priced at 90% for December.
- 10Y JGB: 3.092%, versus just above 3% prior.
- USD/JPY: high of 158.44, versus ~158 prior.
- Tokyo core CPI: 3.0%.
- Read: JGB spillover adds to upward pressure on global long yields.
- For European-listed companies: repatriation risk from Japanese investors is a factor for euro duration and credit funding.
China
- CPI, PPI, export growth and USD/CNY are all unavailable this run.
- The US-China tariff truce, expiring 10 Jan 2027, may reduce trade diversion toward Europe.
- For European-listed companies: the goods-deflation channel cannot be updated this run.
Other EM
- India (RBI repo, CPI) and Russia are unavailable this run.
- No EM signal can be read for European-listed companies.
Analytical framework output — educational tool only, not financial advice. Do your own research.